Japan’s ¥1.3 Million Income Wall: What Changed for Dependent Coverage?
Employer certification, contract-based dependent assessment, employment-based health and pension enrollment and the timing of tax changes in Japan
Read Japan’s permanent employer-certification arrangement alongside the conditional April 2026 contract-assessment method. Two diagrams separate dependent eligibility, employment enrollment and the timing of tax changes.
TL;DR
- Permanence does not remove individual-use conditions
- Contract assessment requires qualifying income and documents
- Check employment enrollment first; distinguish tax-year application from commencement
The image is an AI-generated fictional consultation desk, not a photograph documenting a real workplace or individual case.
This article provides general information about published arrangements, not an individual dependent-coverage determination, legal advice or tax advice. Confirm eligibility with the insurer or pension office and tax application with the official tax office; consult a qualified lawyer or tax accountant about individual judgments.
What Is Happening
Separate certification, contract assessment and enrollment
Making an income-threshold measure permanent sounds reassuring. Yet permanence does not mean that the same worker can submit an employer certificate indefinitely, or that every increase in earnings can be ignored. Another change, introduced in April 2026, allows some dependent-coverage decisions to use earnings specified in employment contracts. These changes address different questions: how long an arrangement continues, when a certificate can be used, and how an insurer estimates income.
changed the employer-certification arrangement from a temporary response into an ongoing arrangement. It also expressly retained the previous operational approach. A continuing scheme therefore does not guarantee unlimited use by an individual.
The contract-based assessment is a separate route with conditions, including receiving only salary income and having contract information that permits an annual estimate. Its availability is not determined simply by counting previous employer certificates. The two arrangements can nevertheless meet: an insurer may request a certificate to investigate temporary additional income.
There is a third question to ask first. Does the worker qualify for health insurance and Employees' Pension Insurance through their own employer? Someone who must enroll through employment cannot choose to remain a spouse's dependent merely because annual earnings are below the dependent-income threshold. Establishing that route before discussing dependent status makes the subsequent questions clearer.
This article uses sources checked as of November 4, 2026, focusing mainly on salary earners considering coverage as a spouse's dependent. It does not determine an individual's eligibility or offer a universal earnings figure at which working more becomes financially advantageous. Tax, dependent coverage and employer family allowances need separate assessments.
Background & Context
Read income, document and commencement conditions
Permanent arrangements retain operational conditions
sets a general limit of two consecutive uses for the same person. Where income is checked annually, this corresponds to using the certificate in the confirmations for two successive years. The count concerns confirmations using the certificate, rather than birthdays of the scheme or every separate payslip. An insurer with a different checking schedule needs to explain how the relevant periods are handled.
The permanence notification did not remove that operational limit. Some introductory passages in the Q&A still describe the arrangement at its original launch. Those passages should be read alongside the newer notification when considering the scheme's duration. Neither “the scheme will necessarily end” nor “there is now no individual limit” follows from reading one of these documents in isolation.
A certificate does not turn a lasting basic-pay increase, a permanent allowance or longer contracted hours into a temporary fluctuation. Submission also does not guarantee dependent status where projected earnings are persistently above the relevant criterion or other eligibility conditions fail. Conversely, having used a certificate twice does not alone establish automatic loss of coverage in a third year. Current income expectations and the applicable assessment route still have to be checked.
Contract assessment changes the evidence used for an estimate
provides a method for people whose income consists only of salary. Earlier assessments already estimated future income using past and current information. The change is therefore not a complete switch from retrospective accounting to forward-looking assessment. It changes which information supports the estimate, with the aim of making decisions easier to anticipate.
states the ordinary income criterion as less than ¥1,300,000 a year (¥1.3 million). Salary for this purpose includes allowances and bonuses. It is not take-home pay or the taxable-income amount after tax deductions.
Financial maintenance remains relevant. For people living together, income is normally less than half the insured person's annual income. An exception may apply when it does not exceed that annual income and the insured person is recognized as the main household maintainer. For people living separately, remittances matter. Meeting the annual-income criterion alone is insufficient.
Different criteria exist for particular age groups and certain disabilities. The special younger-person criterion excludes spouses, so it should not be applied automatically to a younger spouse. The comparison below concerns the ordinary spouse-focused questions; it does not compress every family relationship and exception into one universal amount.
Employer certification
- Circumstances
- Reasons for a temporary increase
- Duration
- Permanent scheme; retained operations
- Use
- General consecutive-use limit
Contract assessment
- Income evidence
- Salary only; calculable contracts
- Documents
- Contract and worker's declaration
- Follow-up
- Renewals and income confirmation
Summary of MHLW notifications and Q&As. Neither arrangement guarantees dependent coverage without conditions; the insurer determines individual eligibility.
Some contracts cannot support the calculation
explains that documents may not permit an annual estimate, including where hours are described only as shift-based or the contract lasts less than a year. In such cases, assessment uses the previous approach with documents such as payslips and tax certificates. This is not a blanket exclusion of all shift workers: what the contract actually establishes matters.
For multiple jobs, the relevant contracts must be provided and the calculated amounts combined. Missing documents, or an inability to calculate income for one workplace, require the previous assessment approach. Pension or business income also prevents a person from simply using the salary-only route. That does not itself prove that a separate employer-certification arrangement can never help with a temporary rise in salary income.
Employment enrollment and tax remain separate
confirms that the monthly-wage condition for part-time-worker enrollment was removed on October 1, 2026. Separate conditions concerning contracted working hours, enterprise size and student status remain. The announcement also identifies special treatment for workers subject to an authorized minimum-wage reduction. “Everyone working twenty hours enrolls” is an incomplete summary.
describes the future staged reduction and removal of the enterprise-size criterion. That criterion did not disappear on the date the wage condition was removed. There are also enrollment routes involving hours and days closer to those of ordinary employees. Checking only the part-time-worker criteria cannot resolve every employment-enrollment case.
Tax figures follow another timetable. states a salary-only income condition of ¥1,360,000 or less (¥1.36 million), subject to the other requirements. This amount commences on December 1, 2026 and applies to the 2026 tax year. Monthly processing before commencement and annual tax calculations should not be presented as changes effective on the same date. Someone outside the spouse deduction may qualify for the separate special spouse deduction.
The agency's gives ¥1,780,000 or less (¥1.78 million) as the salary amount at which no individual and related tax arises when there is no other income. The same commencement and tax-year distinction applies. This figure does not establish dependent-health-insurance eligibility, eliminate resident tax, or determine an employer's family allowance.
Reading the Structure
Compare coverage, budgets and continuing communication
Establish the route before comparing household finances
Leaving dependent coverage does not always mean joining National Health Insurance and the National Pension. Some people enroll in health insurance and Employees' Pension Insurance through their employer. Equally, leaving dependent status does not guarantee eligibility through an employer. The enrollment route and the person's age and circumstances must be established before comparing the resulting costs.
A household comparison should include earnings, insurance contributions, tax and family allowances, rather than contributions alone. Amounts depend on the actual conditions, so a uniform reduction in take-home pay or a universal break-even salary is misleading. Pension entitlements and conditional protection during sickness or maternity-related absence belong in the comparison as separate considerations, not as cash immediately available for this month's bills.
Check dependent coverage
- First question
- Is employment enrollment required?
- Income
- Contracts, fluctuations, other income
- Maintenance
- Household and remittance conditions
Check life after transition
- Coverage route
- Employer insurance or another system
- Budget
- Pay, contributions, tax, allowances
- Protection
- Pension and benefit conditions
Proposed structure for preparing a consultation, not measured financial outcomes. Compare the actual enrollment route, age, household and contract conditions.
Continue communicating changes
Contract assessment does not end after one document submission. Renewals and changes require updated documentation, including a renewal that leaves the wage and working days unchanged. A document filed at the outset is not permission to retain the same decision after any subsequent working arrangement.
Unexpected additional income that ultimately crosses the criterion does not by itself require cancellation where it remains within a socially reasonable range. Artificially understating wages or hours is a different matter. The Q&A does not provide a universal monetary margin that can be treated as a guaranteed safe overrun.
Separating contract changes, unanticipated extra work and new non-salary income helps identify what must be explained. An employer's personnel staff and the insurer assessing dependent coverage have different roles. Understanding a threshold is not enough if the worker does not know which organization needs an update or when another confirmation will occur.
Evaluate changes in life, as well as administrative activity
More working hours alone do not demonstrate that the worker has reached their preferred arrangement. Health, caregiving and travel time can affect that choice. These are questions for evaluation, not evidence that this article has established a particular causal effect of the reforms.
One possible approach is to examine cases where contract information was insufficient, alongside successful submissions. Completed consultations and workers who understood the reason and could proceed are different records. Counting dependent-status retention as the only success could also misclassify a chosen transition into employment coverage as failure.
Here, an means specifying what improvement would look like in the worker's circumstances. It could concern understanding, planning, preferred hours or relevant protection. It should not become a target for directing everyone toward one insurance route, or a substitute for asking about the person's own experience.
Related reading
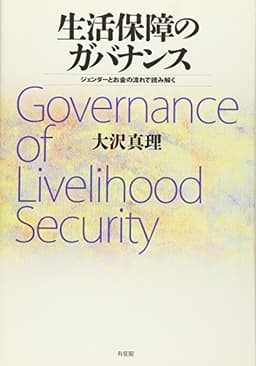
presents Mari Osawa's 生活保障のガバナンス -- ジェンダーとお金の流れで読み解く(外部サイト、新しいタブで開きます) (Governance of Livelihood Security), using the publisher's English title in translation, as a book about livelihood protection and the flow of money through a gender perspective. The full book was not reviewed here. It is related reading rather than evidence for a 2026 administrative decision. The Amazon link is an Associates advertising link.
The guide to designing outcome indicators(このサイトの記事) also discusses distinguishing activity from changes in people's lives.
Remaining Questions
Match populations and periods; examine changes in daily life and unresolved conditions.
Who benefits from a more predictable decision based on employment contracts? Clearly specified hours and a schedule determined later produce different documentation problems. Keeping the previous method available does not establish that every worker understands the difference or can gather the additional evidence. An evaluation should examine contract information and explanations, rather than attributing difficulties only to the individual's knowledge. People who never reach a consultation remain outside records of successful users.
How far can a worker anticipate the financial and insurance consequences of leaving dependent coverage? Employer enrollment and other routes differ in benefits and procedures. Future protection matters, but explaining it does not provide money to meet today's contributions. Family allowances, additional hours and the timing of administrative changes need to be discussed together. A useful consultation also leaves room for the worker to say that a proposed working arrangement does not fit their health or caring responsibilities.
Which result should count as success: retaining dependent status, enrolling independently, or increasing hours? Choosing one direction alone can obscure the worker's preference. Understanding the explanation and knowing what happens at the next confirmation are also meaningful questions. Collecting this information creates its own workload and privacy concerns, so the records should be chosen for a clear purpose and refusal should not become a disadvantage. Beyond announcing revised amounts, can institutions continue providing explanations that help people organize their lives?
References
Making Employer-Certified Dependent-Coverage Assessment Permanent — Ministry of Health, Labour and Welfare (2025). Ministry of Health, Labour and Welfare
Employer-Certified Dependent-Coverage Assessment: Q&A — Ministry of Health, Labour and Welfare (Checked October 2026). Ministry of Health, Labour and Welfare
Dependent-Coverage Assessment Where Annual Contract Income Is Below the Criterion — Ministry of Health, Labour and Welfare (2025). Ministry of Health, Labour and Welfare
Annual Contract-Income Assessment: Q&A — Ministry of Health, Labour and Welfare (2026). Ministry of Health, Labour and Welfare
Dependent-Coverage Assessment Using Annual Income Specified in Employment Contracts — Japan Pension Service (2026). Japan Pension Service
Part-Time-Worker Social Insurance Wage Requirement Removed in October 2026 — Japan Pension Service (2026). Japan Pension Service
Pension System: Expanded Employee Insurance Coverage, Part 9 — Ministry of Health, Labour and Welfare (Checked October 2026). Ministry of Health, Labour and Welfare
No.1191: Spouse Deduction — National Tax Agency (2026). National Tax Agency
Tax Information for Daily Life: Family and Tax — National Tax Agency (2026). National Tax Agency
生活保障のガバナンス -- ジェンダーとお金の流れで読み解く — 大沢真理 (2014). Yuhikaku public bibliography and introduction
Statistics cited in this article
- 1Japan Pension Service: annual income assessment using employment contracts(2026) Open source
- 2National Tax Agency No.1191: spouse deduction(2026 tax year; December 1 commencement) Open source
- 3National Tax Agency: Family and Tax(2026 tax year; December 1 commencement) Open source
Questions to Reflect On
- Who can provide sufficiently clear contract information?
- Who explains budgets and protection after a transition?
- Does administrative activity show the worker’s preferred outcome?
Key Terms in This Article
- Income Tax
- A national tax levied on the income an individual earns over a year, structured progressively so that the rate rises with income. It is distinct from national income, which measures the total income of an economy: one is a tax, the other a measure of economic scale.
- Outcome Indicator
- A measure intended to examine changes or benefits relevant to the problem a program seeks to address. Its design distinguishes outcomes from immediate activity outputs; improvement in a measure alone does not establish the program's causal effect.
Related Content
Japan’s 79.6% Pension Payment Rate: Does It Mean More People Paid?
An examination of fiscal 2025 statistics and scheme explanations, distinguishing contribution months, enrolment categories and benefit consequences.
Can Japan’s Mental-Disorder Workers’ Comp Award Count Rise While the Recognition Rate Falls?
On FY2025 claims, decisions and awards, and the prevention effects these statistics cannot establish

Gender Equality and Organizational Design — A Practical Guide
A practical guide to concrete methods for embedding gender equality into organizational operations at NPOs, municipalities, and businesses.
Series: Organization Design & Resilience
When can municipal disaster staff rest? Health checks, handovers and support
About staff health, rest, handovers and receiving support, drawing on DOHAT activity in Kumamoto in 2026 and public continuity and reception handbooks
Previous
Japan's Comprehensive Support Act for Persons with Disabilities — Two Years into the Operational Phase
Next
Japan's Second-Hand Smoke Law Seven Years In — The Revised Health Promotion Act and Regional Variation in Indoor-Smoking Rules
Get new columns by email
1-2 social structure analysis columns per week. Free to subscribe.
Join ISVD's activities?
Sign up to receive the latest research and activity reports. Feel free to reach out about collaboration or project participation.
Support ISVD’s research and activities
Support ISVD’s research and publications with JPY5,000 per year. There is no automatic renewal.